The Business Models Behind Banking as a Service
Introduction: Banking as a Service Moves to Center Stage!
Wow, so Banking as a Service (BaaS) has at last shifted from a niche infrastructure play to a central pillar of digital finance, reshaping how financial products are designed, distributed, and experienced across global markets. For many of the new financially focused tech professionals coming back here, where the intersection of technology, finance, and business strategy is the core focus, BaaS is no longer an abstract buzzword but a concrete set of business models that determine who captures value in the evolving financial ecosystem, who bears the regulatory and operational risk, and how new entrants can compete with established institutions.
At its core, BaaS allows non-bank companies to integrate regulated financial services directly into their own products via APIs, leveraging the licenses, balance sheets, and compliance capabilities of regulated banks and specialist providers. This architecture underpins everything from embedded payments in e-commerce platforms to fully branded digital banking experiences delivered by retailers, technology firms, and mobility platforms. Understanding the business models behind BaaS therefore requires analyzing how banks, fintechs, platforms, and technology providers share revenue, costs, data, and risk, and how these arrangements are being reshaped by regulation, macroeconomic shifts, and advances in artificial intelligence.
Defining BaaS: From Infrastructure to Revenue Engine
BaaS can be distinguished from traditional banking outsourcing and from higher-level embedded finance by the degree of modularity and programmability it offers. Instead of bespoke integrations, BaaS providers expose standardized APIs that enable partners to launch accounts, cards, lending products, and compliance workflows in weeks rather than years. The most advanced platforms combine core banking, payment processing, risk management, and data analytics into a unified, developer-friendly stack.
In markets such as the United States, the United Kingdom, and the European Union, this model has been accelerated by open banking and open finance initiatives. Regulatory frameworks like the EU's PSD2 and the UK's Open Banking standards have normalized secure data sharing and API-based access to financial services, while in markets such as Singapore and Australia, proactive regulators have encouraged experimentation with digital banks and platform-based models. For global context, readers can explore how regulators frame these developments through organizations such as the Bank for International Settlements and the International Monetary Fund.
On FinanceTechX's fintech coverage, BaaS is increasingly discussed not merely as a technology enabler but as a strategic lever that allows businesses in retail, mobility, SaaS, and even manufacturing to unlock new revenue streams, deepen customer engagement, and gather richer data on user behavior. The business models behind BaaS, therefore, must be evaluated from the perspective of both regulated institutions and non-bank brands that are effectively becoming financial distributors.
The Core BaaS Stakeholders and Value Chain
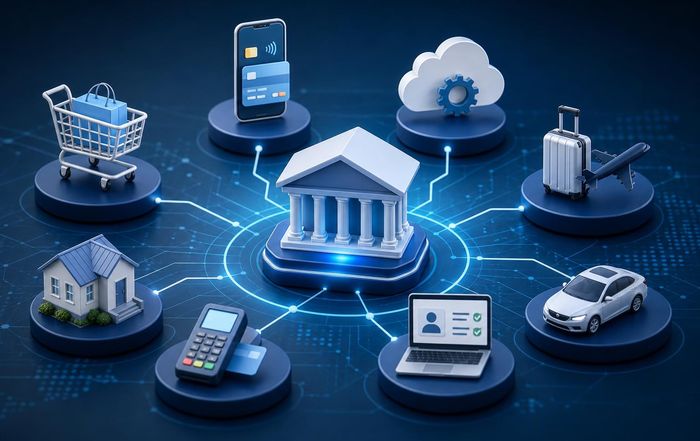
The BaaS value chain typically involves four primary stakeholder groups, each with distinct incentives and business models. First are the licensed banks, often regional or specialized institutions, that provide the regulatory umbrella, hold deposits, and manage capital and liquidity. Second are the BaaS technology platforms that abstract away banking complexity into APIs, developer tools, and compliance workflows. Third are the non-bank brands-retailers, marketplaces, SaaS providers, and technology companies-that embed financial services into their core user journeys. Fourth are the end customers-consumers and businesses-who may not even realize that a regulated bank sits behind the brand they interact with.
In many cases, the BaaS provider and the licensed bank are separate entities, with the platform acting as an intermediary that orchestrates multiple bank partners across regions. In other cases, particularly in Europe and North America, some banks have built their own BaaS platforms, seeking to monetize their infrastructure and licenses directly. The experience and expertise of these players, and the way they structure their revenue models, determine their competitiveness and resilience, especially as regulators in the United States, the United Kingdom, and the European Union scrutinize BaaS arrangements more closely.
Successful individuals focused on the broader business and macroeconomic context can situate BaaS within the business analysis and economy coverage, where the platformization of finance is examined alongside trends in interest rates, credit cycles, and digital transformation.
Revenue Models for Banks Offering BaaS
For licensed banks, BaaS represents both an opportunity to diversify revenue and a challenge in managing risk at scale. The primary revenue streams typically include interest income on deposits and lending products originated through partners, interchange and transaction fees on payment flows, platform or access fees charged to BaaS providers or directly to brands, and revenue-sharing arrangements on specific products such as credit lines or subscription-based accounts.
In the low-interest-rate environment that characterized much of the 2010s, many BaaS strategies focused heavily on fee-based income and interchange, particularly in card-based models in markets like the United States. However, as central banks including the Federal Reserve, the European Central Bank, and the Bank of England adjusted monetary policy in response to inflationary pressures in the early 2020s, net interest margins became more significant again, reshaping how banks evaluated the economics of BaaS partnerships. Deposit-rich BaaS programs that attracted stable, low-cost funding became particularly attractive, especially when paired with robust risk management and compliance controls.
Banks that have successfully built BaaS businesses typically leverage their security in areas such as anti-money laundering, credit risk, and operational resilience, while relying on partners to drive customer acquisition and product innovation. In markets like Germany, the Netherlands, and the Nordic countries, where regulatory expectations are stringent and customers are highly sensitive to data protection, the reputational capital of established banks can be a decisive factor in winning BaaS mandates, especially from large technology or retail brands.
Platform-Centric BaaS Providers and Their Economics
Alongside banks, a growing cohort of specialist BaaS platforms has emerged, particularly in the United States, the United Kingdom, and Singapore, positioning themselves as technology-first intermediaries that connect multiple banks to multiple brands. Their business models typically revolve around usage-based pricing for API calls and transaction volumes, onboarding and implementation fees for new programs, and recurring platform fees for ongoing support, compliance tooling, and data services.
These platforms often invest heavily in developer experience, documentation, sandbox environments, and integration tooling, reflecting a belief that superior experience for product and engineering teams at client companies is a key differentiator. Many operate with a multi-bank strategy, allowing brands to expand across geographies by leveraging different underlying banks while maintaining a consistent API layer. This approach is particularly valuable for global companies operating across Europe, North America, and Asia-Pacific, which must navigate divergent regulatory regimes and payment infrastructures.
From a financial perspective, the most successful BaaS platforms balance the scalability of software economics with the capital and compliance intensity of banking partnerships. They must maintain robust vendor risk management, data security, and resilience standards, aligning with frameworks such as those promoted by the Financial Stability Board and national regulators. As covered in recently updated FinanceTechX's security section, the operational and cyber risks associated with concentrated financial infrastructure providers have become a priority topic for supervisors, especially as BaaS platforms host increasingly critical payment and identity functions.
Embedded Finance and Brand-Led BaaS Strategies
For non-bank brands-ranging from e-commerce giants in the United States and Europe to mobility platforms in Southeast Asia and software providers in Canada and Australia-the business case for BaaS is typically framed around deepening customer relationships, increasing lifetime value, and capturing a share of financial value that would otherwise accrue to third-party banks or payment providers. Rather than launching standalone financial apps, these companies embed banking features directly into existing user journeys, such as offering instant settlement accounts to marketplace sellers, branded debit or credit cards to loyal customers, or working capital loans to small businesses using their platforms.
The revenue models for these brands often combine interchange and revenue share from card programs, interest income or revenue share from lending products, subscription fees for premium financial features, and indirect benefits such as reduced churn, higher transaction volumes, and richer data for personalization. In some cases, particularly in Europe and Asia, large brands have pursued their own e-money or digital banking licenses, but many still rely on BaaS providers to accelerate time to market and manage regulatory complexity.
For founders and executives exploring these opportunities, FinanceTechX's founders hub provides strategic perspectives on when to build versus partner, how to structure BaaS agreements, and how to align incentives between banks, platforms, and brands. The most successful embedded finance strategies are typically those where the financial product is tightly aligned with the core value proposition of the platform, rather than being bolted on as an ancillary feature.
Geographic Variations in BaaS Adoption and Models
The evolution of BaaS business models is heavily influenced by geography, regulatory frameworks, and market structure. In the United States, a combination of community and regional banks, a relatively fragmented regulatory environment, and a strong venture-backed fintech ecosystem has produced a rich BaaS landscape, but also heightened regulatory scrutiny. Supervisors such as the Office of the Comptroller of the Currency and the Federal Deposit Insurance Corporation have increasingly emphasized the need for robust third-party risk management and clear delineation of responsibilities in BaaS relationships.
In the United Kingdom and the European Union, open banking regulations and harmonized payments frameworks have facilitated API-driven models, but capital and conduct rules have also encouraged banks and platforms to formalize their BaaS strategies. Markets like Germany, France, and the Netherlands have seen a mix of bank-led and independent-platform approaches, while Nordic countries such as Sweden, Norway, Denmark, and Finland have leveraged their advanced digital identity and payment infrastructures to enable sophisticated embedded finance use cases.
In Asia-Pacific, countries such as Singapore, Japan, South Korea, and Australia have taken proactive regulatory stances, often encouraging digital bank licenses and innovation sandboxes that intersect with BaaS models. Emerging markets in Southeast Asia, including Thailand and Malaysia, have seen BaaS used to accelerate financial inclusion and support SME financing, while in Africa and South America, including South Africa and Brazil, mobile-first and super-app ecosystems are integrating BaaS to serve underbanked populations and cross-border commerce. Well travelled people interested in cross-border dynamics can refer to the world section, which tracks regulatory developments and market innovations across continents.
Risk, Compliance, and Trust as Strategic Differentiators
While the commercial promise of BaaS is substantial, the sustainability of its business models hinges on robust governance, risk management, and compliance. As BaaS arrangements create multi-layered chains between banks, platforms, and brands, regulators in North America, Europe, and Asia have become increasingly concerned about operational resilience, anti-money laundering controls, and consumer protection. Failures in one part of the chain can quickly erode trust across the ecosystem, especially when end customers are unaware of the underlying bank relationships.
Institutions that succeed in BaaS often treat compliance not as a cost center but as a core element of their value proposition. They invest in advanced transaction monitoring, identity verification, and fraud prevention technologies, frequently leveraging research and standards from bodies such as the Financial Action Task Force and data protection authorities like the European Data Protection Board. The ability to demonstrate strong trustworthiness in areas like data security and privacy, while also offering flexible and developer-friendly APIs, is becoming a key differentiator in winning high-quality partners.
On FinanceTechX's banking coverage, BaaS is increasingly discussed through the lens of operational risk, third-party dependency, and regulatory expectations, reflecting the reality that banks cannot outsource accountability even when they outsource technology or distribution.
The Role of Artificial Intelligence in Optimizing BaaS
By 2026, artificial intelligence has become deeply embedded in BaaS operating models, influencing everything from credit underwriting and fraud detection to customer support and operational automation. AI-driven analytics enable BaaS providers and their partners to segment customers more precisely, tailor product offerings, and dynamically adjust risk parameters based on real-time behavior and macroeconomic signals. For example, machine learning models can help predict default risk in SME lending programs embedded in e-commerce platforms, allowing for more nuanced pricing and credit line management.
At the same time, the use of AI in financial decision-making raises important questions about fairness, explainability, and regulatory oversight. Supervisors in the United States, the European Union, and Asia are increasingly issuing guidance on responsible AI in finance, with institutions looking to frameworks from organizations such as the OECD and the World Economic Forum for best practices. On the new AI section, these developments are analyzed with a focus on how BaaS providers can harness AI for competitive advantage while maintaining transparency and regulatory compliance.
AI also plays a crucial role in operational efficiency for BaaS platforms, enabling automated onboarding, document processing, and real-time anomaly detection in API usage. This allows providers to scale their operations across multiple regions and partners without proportional increases in headcount, improving the unit economics of BaaS and making smaller or more specialized programs commercially viable.
Talent, Jobs, and Organizational Capabilities in BaaS
The growth of BaaS has significant implications for the financial services job market and for the capabilities that banks, fintechs, and technology companies must cultivate. BaaS models demand cross-functional teams that combine deep regulatory and risk expertise with advanced software engineering, product management, and data science skills. Banks that historically operated in siloed, product-centric structures have had to adapt to platform-oriented models, where API reliability, developer experience, and partner success are as important as traditional balance sheet management.
For professionals and organizations tracking these shifts, FinanceTechX's jobs section highlights emerging roles such as BaaS partnership managers, embedded finance product leads, and regulatory technology architects. In markets like the United States, the United Kingdom, Germany, and Singapore, demand for talent with experience in both banking regulation and cloud-native architecture has outpaced supply, leading to intense competition and cross-industry mobility between banks, fintechs, and big technology companies.
Education and continuous learning are therefore critical, with universities, business schools, and professional associations updating their curricula to cover topics such as API strategy, digital identity, and platform governance. Readers interested in the skills dimension can explore the top education coverage, where the intersection of financial literacy, technology fluency, and regulatory understanding is explored in depth.
BaaS, Capital Markets, and Stock Exchange Connectivity
As BaaS matures, its influence extends beyond retail and SME banking into capital markets and stock exchange connectivity. Some BaaS platforms are beginning to offer APIs that facilitate access to brokerage services, fractional investing, and digital asset trading, enabling consumer apps and wealth platforms to embed investment features alongside payments and deposits. This convergence raises strategic questions for traditional brokers and exchanges, as distribution increasingly shifts to digital channels controlled by technology companies and fintechs.
Global exchanges and market infrastructure providers, including those in the United States, the United Kingdom, and Asia, have responded by modernizing their own technology stacks and exploring partnerships with BaaS and embedded finance providers. For successful folks monitoring these dynamics, FinanceTechX's stock exchange section provides analysis on how BaaS is reshaping access to capital markets, particularly for younger investors and small businesses.
Authoritative resources such as the World Federation of Exchanges and the International Organization of Securities Commissions offer additional insight into how regulators and market operators are addressing the opportunities and risks of API-driven market access, including issues related to investor protection, market integrity, and systemic resilience.
Crypto, Green Finance, and the Future Trajectory of BaaS
Although BaaS emerged primarily in the context of traditional fiat banking, its evolution is increasingly intersecting with digital assets, tokenization, and sustainable finance. Some BaaS providers now integrate custody and on-ramp services for cryptocurrencies and stablecoins, allowing brands to offer digital asset features within regulated frameworks. This trend is particularly notable in markets with clear regulatory regimes for crypto assets, such as parts of Europe and Asia, though it remains uneven across jurisdictions.
At the same time, BaaS is being used to scale green finance initiatives, for example by enabling embedded carbon tracking in payment flows, green savings accounts, and sustainable investment products. Organizations such as the United Nations Environment Programme Finance Initiative and the Task Force on Climate-related Financial Disclosures are influencing how financial institutions design and report on such products, while banks and fintechs experiment with models that tie financial incentives to environmental outcomes. Environmental caring people can explore these themes further through FinanceTechX's green fintech and environment coverage, where sustainable innovation and regulatory frameworks are examined in detail.
For those following developments in digital assets and tokenization, a crypto section offers additional independent perspective on how BaaS providers are navigating the complex regulatory and technological challenges of integrating crypto with traditional banking rails, especially in regions such as the United States, the European Union, and Singapore.
Strategic Implications for Founders, Banks, and Investors
For founders and executives in 2026, the central strategic question is no longer whether BaaS will matter, but how to position within its evolving value chain. Banks must decide whether to become BaaS providers, focus on direct-to-consumer and corporate relationships, or pursue hybrid models that leverage their strengths in specific segments or geographies. Technology companies and fintechs must determine when to rely on third-party BaaS platforms, when to negotiate directly with banks, and when, if ever, to pursue their own licenses.
Investors evaluating BaaS opportunities-whether in banks, platforms, or embedded finance brands-need to assess not only growth potential but also the durability of unit economics, the robustness of compliance and risk management, and the resilience of revenue models under different macroeconomic scenarios. Sources such as the Bank for International Settlements and the World Bank provide valuable macro and regulatory context, while FinanceTechX's news section tracks real-time developments in partnerships, regulatory actions, and market shifts.
Ultimately, the business models behind BaaS are not static; they are shaped by regulatory evolution, technological change, and shifting customer expectations across regions from North America and Europe to Asia, Africa, and South America. Organizations that combine deep financial expertise with technological excellence, that treat trust and compliance as strategic assets, and that design BaaS partnerships aligned with clear customer value propositions will be best positioned to thrive in this new era.
Conclusion: BaaS as Infrastructure for the Next Decade of Finance
As 2026 unfolds, BaaS stands as one of the most consequential developments in global finance, acting as the connective tissue between regulated banking infrastructure and the digital experiences that consumers and businesses increasingly expect. For the original news seeking audience coming here today, spanning founders, executives, investors, and policymakers from the United States and United Kingdom to Germany, Singapore, South Africa, and Brazil, understanding the business models behind BaaS is essential to navigating the next decade of financial innovation.
The future trajectory of BaaS will be defined by how effectively stakeholders balance growth with resilience, innovation with regulation, and automation with human judgment. Those who master this balance-leveraging experience, expertise, authoritativeness, and trustworthiness-will not only capture economic value but also help shape a more inclusive, efficient, and sustainable financial system worldwide.
