The Evolution of Digital Lending Platforms
Introduction: Digital Credit at a Global Inflection Point
Digital lending has shifted from a disruptive niche to a core pillar of modern financial infrastructure, reshaping how consumers, small businesses, and institutional borrowers access credit across North America, Europe, Asia, Africa, and South America. What began as experimentation with online loan applications and basic credit scoring models has matured into an interconnected ecosystem of cloud-native platforms, embedded finance, real-time data analytics, and increasingly stringent regulatory oversight. For the professional financial followers here and its global community of founders, executives, investors, and policymakers, understanding this evolution is no longer optional; it is central to strategic decision-making in fintech, banking, capital markets, and the broader digital economy.
Digital lending today encompasses a wide spectrum of models, from consumer buy-now-pay-later solutions and small and medium-sized enterprise (SME) working capital platforms to digital mortgage origination, peer-to-peer marketplaces, and fully integrated embedded credit in e-commerce and enterprise resource planning systems. As explored across FinanceTechX's coverage of fintech innovation, global business transformation, and macroeconomic shifts, these platforms are redefining who can access credit, at what cost, and under which risk and compliance frameworks. This article traces the evolution of digital lending platforms, examines the technological and regulatory forces shaping them, and outlines the implications for financial institutions, founders, and policymakers in the years ahead.
From Online Applications to Platform-Based Credit Infrastructure
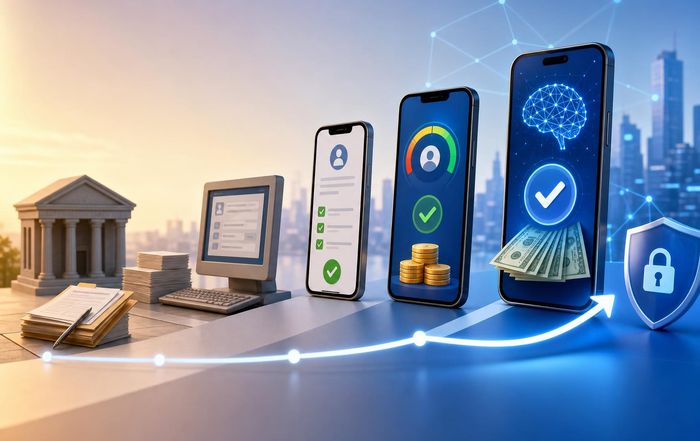
The earliest phase of digital lending in the late 2000s and early 2010s was largely characterized by the migration of traditional loan processes onto the web, with lenders offering online forms, basic document uploads, and limited automation. Pioneers such as LendingClub and Prosper in the United States popularized peer-to-peer lending models, while platforms like Zopa in the United Kingdom and Auxmoney in Germany demonstrated that online marketplaces could match retail investors and borrowers at scale. These platforms leveraged emerging infrastructure such as electronic signatures, online identity verification, and early-stage credit analytics to streamline origination, but much of the underwriting logic remained rooted in conventional credit bureau data and batch-based processing.
As cloud computing and application programming interfaces (APIs) matured, digital lending shifted from being a channel to becoming a platform and, increasingly, a set of modular services that could be embedded into other digital experiences. The rise of open banking frameworks in regions such as the European Union, under regulations like the revised Payment Services Directive (PSD2), accelerated the ability of lenders to access real-time bank account information, transaction histories, and account verification data. Interested readers can explore how open banking standards evolved via resources from the European Banking Authority. This phase marked a deeper integration of data, automation, and connectivity, enabling digital lenders to move beyond static application forms toward dynamic, data-rich underwriting and near-instant credit decisions.
The Data Revolution: Alternative Data, AI, and Real-Time Risk Assessment
The most profound shift in digital lending over the past decade has been the integration of alternative data sources and advanced analytics into core underwriting and risk management workflows. Traditional credit bureaus, while still central in markets such as the United States, United Kingdom, and parts of Europe, have increasingly been augmented by bank transaction data, e-commerce histories, payroll and accounting feeds, telecom usage, and even behavioral and device-level signals. Institutions such as the World Bank have documented how alternative data, when used responsibly, can expand credit access for thin-file and underserved borrowers in emerging markets; more detail is available in their work on financial inclusion.
Artificial intelligence and machine learning models, powered by scalable cloud infrastructure from providers such as Amazon Web Services, Microsoft Azure, and Google Cloud, have enabled lenders to process vast amounts of structured and unstructured data in real time. These models can detect subtle risk patterns, segment borrowers with greater granularity, and dynamically adjust credit limits and pricing. For a deeper technical perspective, practitioners often reference guidance from organizations such as the Bank for International Settlements on the prudent use of AI in financial risk management. At the same time, regulators and consumer advocates have raised concerns about algorithmic bias, explainability, and data privacy, prompting both incumbent banks and fintech platforms to invest heavily in responsible AI frameworks and model governance.
Within this context, FinanceTechX's dedicated coverage of AI in finance has highlighted how leading digital lenders in markets from the United States and Canada to Singapore and Brazil are deploying machine learning models that are not only predictive but also interpretable, supported by rigorous validation, stress testing, and continuous monitoring. The evolution has been from simplistic scorecards to complex yet auditable models that can satisfy supervisory expectations while still delivering competitive advantages in speed and accuracy.
Embedded Lending and the Rise of Invisible Credit
One of the most significant structural changes in digital lending has been the shift from standalone lending destinations to embedded, contextual credit experiences within e-commerce, enterprise software, and consumer applications. Buy-now-pay-later (BNPL) offerings from companies such as Klarna, Afterpay, and Affirm demonstrated that credit could be integrated directly into checkout flows, enabling consumers to split payments over time with minimal friction. Similarly, small businesses increasingly access working capital and invoice financing directly through platforms such as Shopify, Amazon, and leading software-as-a-service (SaaS) accounting tools, rather than approaching banks or traditional lenders.
This embedded finance paradigm, discussed frequently in FinanceTechX's banking and stock exchange and capital markets coverage, has profound implications for competitive dynamics. The providers that own customer relationships and data-large retailers, marketplaces, and software platforms-are increasingly able to originate and distribute credit, often in partnership with regulated banks or licensed lenders operating behind the scenes. Analysts and policymakers can explore this phenomenon further through research from institutions such as the International Monetary Fund and McKinsey & Company on embedded finance and the future of banking.
For borrowers, embedded lending can significantly reduce friction, as credit offers are presented at the moment of need, with pre-populated data and instant decisions. For lenders, it opens new origination channels and richer datasets, but it also requires robust risk-sharing arrangements, clear disclosures, and careful alignment of incentives among platforms, funding partners, and end customers. Regulators in jurisdictions including the United States, United Kingdom, Australia, and the European Union have begun to scrutinize BNPL and other embedded models more closely, seeking to ensure that consumer protections, affordability assessments, and transparency standards keep pace with rapid innovation.
Regulatory Convergence, Consumer Protection, and Data Governance
The evolution of digital lending platforms has not occurred in a regulatory vacuum; rather, it has catalyzed a wave of new rules, supervisory expectations, and cross-border coordination efforts. Authorities such as the U.S. Consumer Financial Protection Bureau (CFPB), the UK Financial Conduct Authority (FCA), and the European Central Bank (ECB) have progressively extended existing consumer credit, fair lending, and anti-money-laundering (AML) frameworks to digital lenders, while also issuing specific guidance on topics such as algorithmic decision-making, digital identity verification, and cross-border data transfers.
In Europe, the convergence of PSD2, the General Data Protection Regulation (GDPR), and the evolving Digital Operational Resilience Act (DORA) has created a complex but increasingly harmonized environment in which digital lenders must manage cybersecurity, data protection, and operational resilience in an integrated manner. Professionals seeking detailed regulatory texts and supervisory statements can consult the European Commission's digital finance pages and the European Central Bank's publications. Similarly, in Asia, regulators in Singapore, South Korea, Japan, and India have issued digital banking and lending frameworks that emphasize risk-based supervision, strong capital and liquidity standards, and rigorous conduct requirements.
For global fintech founders and executives, the regulatory landscape has moved from ambiguous to demanding, but it has also brought greater clarity and legitimacy. FinanceTechX's security and compliance coverage has chronicled how leading digital lenders are investing in enterprise-grade cybersecurity, data encryption, and identity verification technologies, often partnering with regtech providers to automate know-your-customer (KYC), AML, and sanctions screening processes. Resources from the Financial Action Task Force provide additional guidance on best practices for combating financial crime in digital channels, underscoring the importance of global cooperation in an increasingly interconnected financial system.
Business Models, Funding Structures, and the Path to Profitability
The maturation of digital lending platforms has also been marked by a shift in business models and funding structures. Early-stage platforms often relied on marketplace models, matching retail or institutional investors with borrowers and earning origination and servicing fees. Over time, many have diversified into balance sheet lending, securitization, and bank partnerships to achieve scale and resilience. In the United States and Europe, digital lenders have tapped capital markets through asset-backed securities and warehouse lines, while in Asia and Latin America, partnerships with incumbent banks and non-bank financial institutions have become increasingly common.
This evolution has been shaped by macroeconomic conditions, including the low interest rate environment of the 2010s, the unprecedented monetary and fiscal responses to the COVID-19 pandemic, and the subsequent tightening cycles of the early 2020s. As documented in analyses by the Bank of England and the U.S. Federal Reserve, rising interest rates and heightened credit risk have tested the resilience of digital lenders' funding models and risk management practices. For readers of FinanceTechX, the intersection of economy, news, and digital credit has become a central theme, as investors scrutinize unit economics, loss rates, and capital efficiency more closely.
Today, leading platforms in markets such as the United States, United Kingdom, Germany, India, and Brazil are increasingly pursuing diversified revenue streams, including subscription-based software offerings for banks and credit unions, white-label lending-as-a-service (LaaS) solutions for non-financial brands, and data analytics products for institutional investors. This trajectory aligns with a broader shift in fintech from pure balance sheet risk-taking toward platform and infrastructure models, where technology, data, and distribution capabilities generate recurring, higher-margin revenues. Strategic partnerships between digital lenders and incumbent institutions-such as those between Goldman Sachs, Apple, and various BNPL providers-illustrate how traditional and digital players are converging around shared infrastructure and co-branded offerings.
Founders, Talent, and the Global Competition for Expertise
Behind the evolution of digital lending platforms is a generation of founders, product leaders, risk officers, and engineers who have combined deep financial expertise with advanced technical skills. From early pioneers in Silicon Valley and London to emerging leaders in Singapore, Nairobi, São Paulo, and Berlin, these individuals have navigated complex regulatory environments, volatile funding cycles, and rapidly shifting consumer expectations. FinanceTechX's focus on founders and leadership has highlighted the importance of multidisciplinary teams that can bridge the worlds of credit risk, data science, compliance, and user experience.
The competition for talent in digital lending has become global, with banks, fintech startups, big tech firms, and consulting organizations all vying for experienced data scientists, credit modelers, cybersecurity experts, and compliance professionals. As the sector matures, there is growing recognition that sustainable advantage depends not only on cutting-edge algorithms but also on robust governance, ethical frameworks, and continuous professional development. Institutions such as the Chartered Financial Analyst (CFA) Institute and leading universities have expanded their curricula to cover fintech, data analytics, and digital risk management, while online platforms and professional networks facilitate ongoing learning and collaboration.
For professionals and job seekers tracking opportunities in this space, FinanceTechX's jobs and careers section complements broader labor market insights from organizations such as the OECD and the World Economic Forum, which have documented the growing demand for digital skills in financial services and the need for reskilling and upskilling across regions.
Regional Dynamics: United States, Europe, Asia, Africa, and Beyond
While digital lending has become a global phenomenon, its evolution has followed distinct trajectories across regions, shaped by regulatory frameworks, banking structures, technology adoption, and consumer behavior. In the United States, a large and fragmented banking system, deep capital markets, and robust venture ecosystems have supported a diverse array of platforms, from consumer lenders and SME specialists to mortgage technology providers and BNPL firms. Regulatory complexity, however, with overlapping federal and state regimes, has required sophisticated legal and compliance capabilities.
In Europe, the combination of PSD2-driven open banking, GDPR, and a strong emphasis on consumer protection has fostered a collaborative environment in which banks, fintechs, and payment service providers increasingly co-innovate. Markets such as the United Kingdom, Sweden, the Netherlands, and Germany have produced globally influential digital lenders and infrastructure providers, while the European Union's digital finance strategy seeks to harmonize cross-border activity. Interested readers can learn more about these initiatives through resources provided by the European Commission and regional supervisory authorities.
Asia has emerged as a crucible of innovation in digital lending, with super-app ecosystems in China and Southeast Asia, advanced digital banking frameworks in Singapore and South Korea, and rapid fintech adoption in India and Indonesia. Platforms associated with Ant Group, Tencent, Grab, GoTo, and Paytm have demonstrated the potential of integrating payments, lending, wealth management, and lifestyle services within single ecosystems. At the same time, regulators in China and other markets have taken steps to curb excessive leverage and systemic risk, underscoring the need for balanced growth. Africa and Latin America, meanwhile, have seen digital lending play a critical role in expanding access to credit for SMEs and underbanked populations, often in tandem with mobile money and digital identity solutions. Organizations such as the Bill & Melinda Gates Foundation and the Alliance for Financial Inclusion have documented these developments and their implications for inclusive growth.
For a global readership, FinanceTechX's world and regional coverage contextualizes these regional stories within broader macroeconomic and geopolitical trends, helping decision-makers understand how regulatory shifts in one jurisdiction can reverberate across international portfolios and cross-border partnerships.
Intersections with Crypto, DeFi, and Green Finance
As digital lending platforms have matured, they have increasingly intersected with other transformative trends in finance, including cryptoassets, decentralized finance (DeFi), and sustainable and green finance. While the exuberance of the 2021-2022 crypto boom has been tempered by regulatory scrutiny and market corrections, the underlying technologies of tokenization, smart contracts, and decentralized identity continue to influence how innovators think about collateral, settlement, and programmable credit. Institutions such as the Financial Stability Board and the International Organization of Securities Commissions (IOSCO) have issued guidance on the risks and opportunities associated with crypto-based lending and DeFi platforms, emphasizing the need for robust investor protections and systemic risk safeguards.
On FinanceTechX, the crypto and green fintech sections explore how tokenized assets, carbon markets, and sustainability-linked loans are reshaping credit markets and investor expectations. Digital lenders are beginning to integrate environmental, social, and governance (ESG) metrics into underwriting and portfolio management, aligning with global initiatives such as the United Nations Principles for Responsible Banking and climate disclosure frameworks promoted by the Task Force on Climate-related Financial Disclosures (TCFD). In markets across Europe, North America, and Asia-Pacific, banks and fintechs are experimenting with green loans, impact-linked credit pricing, and partnerships that support energy efficiency, clean transportation, and sustainable supply chains.
The convergence of digital lending and sustainability raises complex questions about data quality, standardization, and verification, particularly as regulators and investors demand more rigorous evidence of environmental and social impact. FinanceTechX's environment and sustainability coverage provides ongoing analysis of how lenders, rating agencies, and technology providers are responding, and how these developments influence asset allocation, risk management, and corporate strategy.
Education, Trust, and the Future of Digital Credit
As digital lending becomes more deeply embedded in everyday life and business operations, the importance of financial literacy, transparency, and trust cannot be overstated. Consumers and SMEs in markets from the United States and Canada to South Africa and Malaysia must navigate complex choices among traditional banks, digital-only lenders, BNPL providers, and embedded credit offers within e-commerce and software platforms. Misunderstandings about interest rates, fees, repayment obligations, and data usage can lead to overindebtedness and reputational risks for providers.
Educational initiatives from central banks, consumer protection agencies, and non-profit organizations, as well as industry-led standards and codes of conduct, play a crucial role in fostering responsible borrowing and lending. Resources from the OECD's financial education programs and national regulators such as the Monetary Authority of Singapore provide valuable frameworks for designing effective financial literacy campaigns and disclosure standards. Within this context, FinanceTechX's focus on education and thought leadership aims to equip readers with the knowledge needed to evaluate digital lending offerings, assess risk, and make informed strategic decisions.
Trust in digital lending also hinges on robust cybersecurity, data protection, and incident response capabilities. As platforms handle sensitive personal and financial data, they become attractive targets for cybercriminals and state-sponsored actors. Collaboration between industry, regulators, and cybersecurity experts, guided by best practices from organizations such as the National Institute of Standards and Technology (NIST), is essential to maintaining resilience and public confidence. FinanceTechX's security-focused reporting underscores that, in an era of sophisticated threats, security is not a peripheral concern but a core component of product design, governance, and brand integrity.
Conclusion: Strategic Imperatives for the Next Decade
Digital lending platforms have moved from the periphery of financial services to its center, influencing how capital flows across sectors, regions, and asset classes. The evolution has been driven by advances in data and AI, the rise of embedded finance, regulatory convergence, and the entrepreneurial energy of founders and teams across the globe. At the same time, it has surfaced critical challenges around fairness, transparency, cybersecurity, and systemic risk that demand ongoing attention from industry leaders and policymakers.
For the business audience online, several strategic imperatives emerge. First, institutions must treat digital lending not as a standalone product but as a core capability that intersects with payments, wealth management, insurance, and corporate banking, requiring integrated technology and data architectures. Second, competitive advantage will increasingly rest on the ability to balance innovation with robust governance, ensuring that AI models, data practices, and product designs align with evolving regulatory expectations and societal norms. Third, global players must navigate regional nuances in regulation, consumer behavior, and infrastructure, building partnerships and operating models that are both scalable and locally relevant.
As FinanceTechX continues to expand its daily news across fintech, business, economy, world markets, and the broader financial technology ecosystem, the evolution of digital lending will remain a central narrative thread. The next decade will likely see further integration of AI, real-time data, tokenized assets, and sustainability metrics into lending decisions, as well as new forms of collaboration between banks, fintechs, big tech, and regulators. Those organizations that combine technological excellence with deep expertise, strong governance, and a commitment to long-term trust will be best positioned to shape, and benefit from, the future of digital credit.
