The Evolution of Digital Business Banking
From Branch Counters to Cloud Platforms
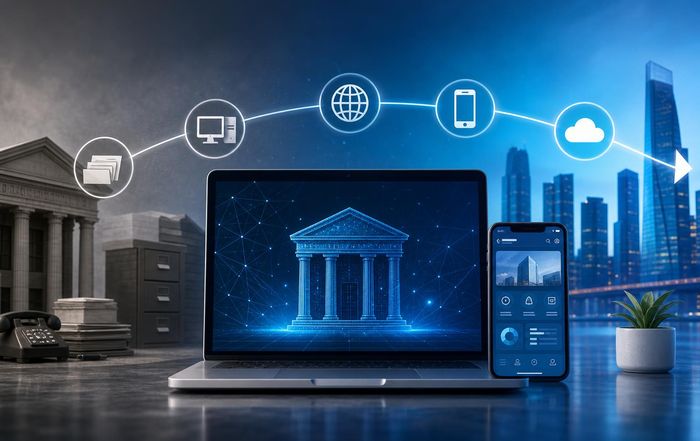
In less than two decades, business banking has moved from paper-heavy branch interactions to always-on digital ecosystems that now shape how companies are founded, financed, scaled and governed across global markets, and for the readers of FinanceTechX this transformation is not an abstract trend but a lived reality that influences daily decisions about liquidity, risk, technology investment and growth strategy. Where once a corporate treasurer in New York, a startup founder in Berlin or a small manufacturer in Singapore depended on local branch managers, faxed mandates and batch payment files, they now operate in a world of real-time APIs, embedded finance, instant cross-border payments and algorithmic credit models that draw on thousands of data points rather than a single balance sheet snapshot.
This shift has not been a simple digitisation of existing processes; instead, it has redefined the business bank itself from a monolithic institution into a distributed stack of regulated balance sheets, cloud-native software, data services and specialised fintech providers, many of which are now covered regularly on the fintech hub as they reshape the competitive landscape. As regulators in the United States, United Kingdom, European Union, Singapore and other leading jurisdictions modernise frameworks for open banking, digital identity and cloud outsourcing, the pace of change has accelerated, creating both opportunity and complexity for businesses of all sizes.
For executives, founders and finance leaders, understanding how digital business banking has evolved-and where it is heading by 2030-is increasingly a prerequisite for sound strategy, not just an operational detail to be delegated to back-office teams.
The First Wave: Online Portals and Core Modernisation
The first wave of digital business banking began in the early 2000s, when large institutions such as JPMorgan Chase, HSBC, Barclays, BNP Paribas and Citigroup introduced online portals that allowed corporate and SME customers to view balances, initiate payments and download statements without visiting branches. At this stage, digital banking largely replicated existing workflows in electronic form, and the underlying core banking systems, many built in the 1970s and 1980s, remained batch-based and inflexible, limiting innovation to cosmetic and channel-level improvements.
Core modernisation slowly followed, driven by margin pressure, regulatory requirements and rising customer expectations set by consumer technology platforms like Amazon and Apple, which popularised intuitive interfaces and instant digital experiences. Industry research from organisations such as McKinsey & Company and Boston Consulting Group began to document the widening performance gap between institutions that invested early in digital capabilities and those that remained branch-centric, especially in transaction banking and cash management where automation and straight-through processing could significantly reduce cost-to-serve.
In parallel, regulators and international standard-setters, including the Bank for International Settlements and the Financial Stability Board, started to examine the systemic implications of digitalisation, from operational resilience and cyber risk to outsourcing concentration in a small number of global cloud providers, setting the stage for the more open and interconnected era that would follow.
The Rise of Fintech Challengers and Embedded Services
The second wave of evolution was defined by the rise of digital-first challengers and specialised fintech providers that targeted specific pain points in business banking, such as cross-border payments, expense management, FX hedging and working capital finance. Companies like Wise, Stripe, Adyen, Revolut Business, Airwallex and Brex built cloud-native platforms that prioritised user experience, rapid onboarding and transparent pricing, often entering markets where incumbent banks had underinvested in digital capabilities for SMEs and high-growth startups.
These challengers leveraged modern technology stacks, including microservices architectures, real-time data processing and open APIs, to integrate seamlessly with accounting platforms such as Xero and QuickBooks Online, as well as with e-commerce ecosystems like Shopify and Amazon Business. The result was a new category of embedded financial services, in which banking functions-payments, lending, cards, treasury tools-were woven directly into the software environments where businesses already operated, reducing friction and manual reconciliation.
For readers of FinanceTechX business insights, this embedded model has profound strategic implications, because it blurs the line between bank, platform and enterprise resource planning system, forcing companies to reconsider which partners they rely on for financial operations and how they manage vendor and counterparty risk. As more financial services are delivered through APIs, the competitive battlefield has shifted from branch networks and relationship managers to developer ecosystems, integration depth and data-driven product design.
Open Banking, APIs and the Platformization of Finance
The introduction of regulatory open banking frameworks, most notably the EU's PSD2 and the UK's Open Banking Standard, accelerated the platformization of business banking by mandating that banks provide secure API access to customer data and, in some cases, payment initiation services. Similar initiatives followed in Australia, Singapore, Brazil and other markets, creating a global trend toward data portability and interoperability that has extended beyond retail into corporate and SME segments.
This shift has enabled new categories of providers-account aggregation tools, cash visibility dashboards, multi-bank treasury platforms and credit analytics engines-to sit on top of existing banking relationships, offering businesses a consolidated view of cash, risk and financing across multiple institutions. Providers such as Tink, Plaid, Yapily and Finicity have become critical infrastructure players, connecting banks, fintechs and enterprises in a complex web of data flows that must be governed carefully to maintain security and trust.
From the perspective of our happy readers who follow changes on the economy and capital flows, open banking has also introduced new competitive dynamics, as banks are compelled to differentiate not only on balance sheet strength and pricing but on the quality and reliability of their APIs, the richness of their data and the sophistication of their digital tools for CFOs and treasurers. In this environment, the most successful institutions are those that embrace platform thinking, positioning themselves as orchestrators of ecosystems rather than closed monoliths.
AI, Data and the Intelligence Layer of Business Banking
By 2026, the evolution of digital business banking is increasingly defined by the intelligence layer that sits atop transactional infrastructure, as advances in artificial intelligence and machine learning reshape credit underwriting, fraud detection, cash forecasting and relationship management. Banks and fintechs alike are deploying AI models that analyse payment histories, invoice flows, payroll data, e-commerce sales and even logistics information to build dynamic risk profiles and offer more tailored products to businesses in real time.
Institutions such as Goldman Sachs, DBS Bank, BBVA and Capital One have publicly discussed their use of AI in areas ranging from anomaly detection to personalised financial insights, while technology companies including Microsoft, Google Cloud and Amazon Web Services provide specialised financial services tooling through their cloud platforms. For deeper context on how AI is transforming financial workflows, readers can explore the FinanceTechX AI section, which tracks developments in generative models, predictive analytics and autonomous finance.
The promise of this intelligence layer is significant: more accurate credit decisions for SMEs with thin files, proactive liquidity management for mid-market companies, automated compliance checks and enhanced detection of cyber threats and payment fraud. However, it also raises complex questions about model governance, data privacy, explainability and algorithmic bias, prompting regulators such as the European Banking Authority and the U.S. Federal Reserve to issue guidance on responsible AI use in financial services.
For business leaders, the key challenge is to harness AI-driven capabilities without surrendering control over critical decisions or exposing the organisation to opaque risks, which requires careful vendor selection, strong internal data governance and an understanding of how models are trained, validated and monitored over time.
Founders, Neobanks and the Reimagining of Business Accounts
One of the most visible manifestations of digital evolution has been the emergence of business-focused neobanks and fintech platforms founded by entrepreneurs who experienced first-hand the limitations of traditional corporate accounts, onboarding processes and international payments. Founders behind companies such as N26, Qonto, Starling Bank, Mercury, Rho and Tide designed their products around the workflows of startups, freelancers, digital agencies and e-commerce merchants, emphasising rapid account opening, integrated cards, automated expense categorisation and seamless connection to accounting tools.
These platforms often operate under banking-as-a-service arrangements or partner with licensed institutions, enabling them to focus on user experience and product innovation while leveraging the regulatory infrastructure of established banks. For the global founder community that FinanceTechX's founders hub serves, this model has materially lowered the friction of starting and scaling a business across borders, allowing teams in Germany, France, Canada, Australia and beyond to access sophisticated financial tools previously reserved for larger corporates.
At the same time, the proliferation of neobanks has intensified competition and raised questions about the sustainability of business models reliant on interchange revenue and low-margin services, especially in a higher interest rate environment. The most resilient players are those that move beyond basic accounts and cards to offer value-added services such as integrated payroll, revenue-based financing, FX risk management and vertical-specific solutions for sectors like SaaS, marketplaces or logistics.
Security, Regulation and the Trust Imperative
As digital business banking becomes more complex and interconnected, security and regulatory compliance have emerged as central determinants of trust, influencing both customer adoption and supervisory scrutiny. Cyber incidents, ranging from ransomware attacks on financial institutions to sophisticated social engineering campaigns targeting corporate finance teams, have underscored the need for robust controls, continuous monitoring and resilient architectures.
Regulators and industry bodies, including the European Central Bank, the Monetary Authority of Singapore and the U.S. Office of the Comptroller of the Currency, have issued increasingly detailed guidelines on topics such as operational resilience, third-party risk management, cloud outsourcing and incident reporting, shaping how banks and fintechs design and operate their digital platforms. In parallel, international standards like ISO/IEC 27001 and frameworks from the National Institute of Standards and Technology provide reference points for best practice in information security.
For organisations using digital banking services, the evolution of security expectations means that vendor due diligence, contractual protections, encryption standards, access controls and data residency considerations must now be treated as board-level issues rather than purely technical concerns. The security channel has increasingly focused on this intersection of cyber risk, regulation and digital finance, reflecting the reality that trust in business banking is now as much about digital resilience as it is about capital ratios and credit ratings.
Jobs, Skills and the Changing Talent Landscape
The digital transformation of business banking has also reshaped the talent landscape, both within financial institutions and across the broader ecosystem of fintechs, technology providers and corporate finance teams. Traditional roles in branch operations and manual back-office processing have declined, while demand has surged for professionals in data science, cloud engineering, cybersecurity, product management and digital compliance, creating new career pathways and skills requirements.
Banks and fintechs in markets such as the United States, United Kingdom, Singapore, India and Brazil are competing aggressively for scarce expertise in AI, API development and user experience design, often partnering with universities and training providers to build talent pipelines. At the same time, finance professionals within corporates are expected to be more technologically literate, comfortable working with dashboards, automation tools and integrated platforms rather than spreadsheets and paper-based workflows.
For individuals and organisations tracking opportunities in this evolving landscape, resources such as the FinanceTechX jobs section and global platforms like LinkedIn and Glassdoor provide insight into emerging roles, required skills and regional hiring trends. The long-term implication is that digital business banking is not just a technology story but a human capital story, in which continuous learning and cross-disciplinary expertise become critical differentiators.
Stock Exchanges, Capital Markets and Real-Time Treasury
Digital business banking does not exist in isolation from capital markets; instead, it increasingly interfaces with stock exchanges, electronic trading venues and digital asset platforms to provide treasurers and CFOs with real-time visibility and control over liquidity, risk and investment. As exchanges such as NYSE, Nasdaq, London Stock Exchange and Deutsche Börse modernise their own infrastructures and data services, banks are integrating market data, execution tools and collateral management capabilities into digital portals and APIs.
For corporates, this means that cash management, short-term investing and hedging strategies can increasingly be executed programmatically, with treasury management systems connecting directly to banking platforms and market venues. The FinanceTechX stock exchange coverage has highlighted how innovations such as real-time payments, instant settlement pilots and tokenised securities are beginning to compress traditional settlement cycles and enable more dynamic working capital management.
In this environment, the boundary between transactional banking and capital markets services is blurring, particularly for mid-sized and large corporates that demand integrated solutions for payments, FX, liquidity, trade finance and securities services. Banks that can orchestrate these capabilities through cohesive digital platforms are better positioned to retain and deepen client relationships, while those that lag risk disintermediation by more agile competitors and specialised providers.
Crypto, Digital Assets and the Edges of Business Banking
Although mainstream business banking remains anchored in fiat currencies and regulated deposit-taking, the rise of cryptoassets, stablecoins and tokenised deposits has begun to influence product development and strategic planning, especially in cross-border payments, treasury diversification and on-chain settlement. Major financial institutions, including JPMorgan with its JPM Coin initiative and Onyx platform, as well as projects like Fnality and central bank digital currency experiments documented by the BIS Innovation Hub, are exploring how tokenised money could increase speed, transparency and programmability in wholesale transactions.
Corporate adoption remains cautious and highly selective, constrained by regulatory uncertainty, accounting treatment questions and risk management considerations, yet interest in tokenised deposits, regulated stablecoins and blockchain-based trade finance continues to grow. For readers tracking these developments, the crypto vertical provides a lens on how digital assets are intersecting with traditional banking, from custody and settlement to compliance and market infrastructure.
Over the coming years, the most likely path is not a wholesale replacement of conventional business banking but a gradual integration of tokenised instruments into specific use cases where they deliver clear efficiency gains and can be governed under robust regulatory frameworks, particularly in cross-border B2B payments, supply chain finance and securities settlement.
Green Fintech, ESG and Sustainable Business Banking
Sustainability has moved from a peripheral concern to a central strategic priority in business banking, as investors, regulators, customers and employees demand more transparent and accountable approaches to environmental, social and governance (ESG) issues. Banks are under pressure to decarbonise their loan books, support clients in the transition to low-carbon business models and improve disclosure of climate-related risks, guided by frameworks from organisations such as the Task Force on Climate-related Financial Disclosures and the International Sustainability Standards Board.
Digital tools are playing a critical role in this transition, enabling more granular measurement of financed emissions, scenario analysis and impact tracking across supply chains. Green fintech startups are emerging with solutions for carbon accounting, sustainable trade finance, ESG-linked lending and green bond verification, often partnering with banks to deliver integrated offerings to corporate clients. For those interested in the convergence of finance and sustainability, both the FinanceTechX green fintech section and the environment channel explore how technology is enabling more credible and data-driven approaches to sustainable business practices.
As regulatory initiatives such as the EU Taxonomy and mandatory climate disclosure regimes in markets like the UK, Canada and New Zealand take effect, digital business banking platforms will increasingly need to incorporate ESG data, reporting tools and advisory capabilities, transforming sustainability from a niche product line into a core dimension of corporate finance.
Convergence, Collaboration and Continuous Innovation
The evolution of digital business banking has reached a point where technology, regulation, customer expectations and competitive dynamics are tightly intertwined, creating a landscape in which no single institution can realistically deliver all required capabilities alone. Instead, the future is likely to be characterised by convergence and collaboration: banks partnering with fintechs and cloud providers; corporates integrating multiple platforms through APIs; regulators engaging with industry to balance innovation and stability; and global ecosystems forming around shared standards and interoperable infrastructures.
For the entrepreneur, thinking professionals here, usually in North America and Europe, the central question is no longer whether digital business banking will dominate, but how to navigate its complexity in a way that enhances resilience, competitiveness and long-term value creation. This requires a strategic approach that treats digital banking relationships as part of a broader financial operating system, encompassing treasury, risk, data, talent and sustainability, rather than as isolated service contracts.
As we continue to expand daily reporting across world markets, banking innovation and the broader news agenda, the platform remains committed to providing the insights, analysis and context that business leaders, founders and policymakers need to make informed decisions in this rapidly evolving environment. The evolution of digital business banking is far from complete, but its trajectory is clear: toward more intelligent, integrated, secure and sustainable systems that will define how businesses manage money and risk in the decade ahead.
