Financial Super Apps Redefining Customer Experience
The Rise of Financial Super Apps as a Global Phenomenon
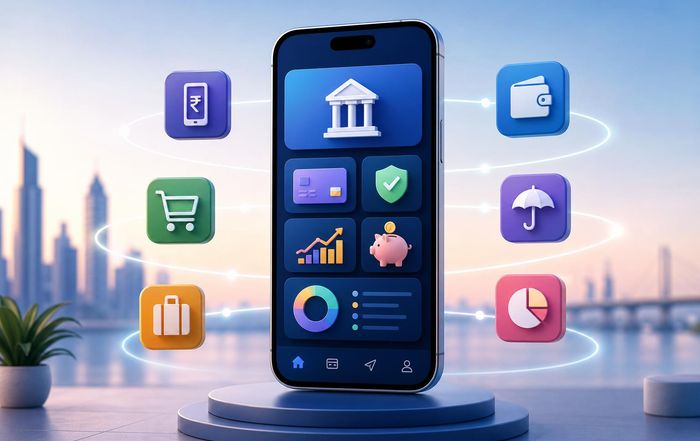
Financial super apps have evolved from experimental platforms into central operating systems for consumers' financial lives, reshaping expectations across banking, payments, investing, and everyday commerce. Originating in Asia with pioneers such as WeChat Pay and Alipay, the super app model has spread rapidly across North America, Europe, and emerging markets, catalyzed by advances in open banking, digital identity, cloud computing, and artificial intelligence. While early digital banking focused on convenience and mobile access, the current wave of financial super apps is redefining customer experience by orchestrating entire financial journeys within a single, data-rich environment.
For decision-makers following events on FinanceTechX, this shift is not a distant trend but an immediate strategic reality. Banks, fintechs, big tech platforms, and even retailers are racing to build or participate in super app ecosystems that promise deeper engagement, lower acquisition costs, and richer data. At the same time, regulators from the U.S. Federal Reserve to the European Central Bank and the Monetary Authority of Singapore are scrutinizing these platforms for systemic risk, competition concerns, and consumer protection issues, recognizing that super apps could become the new critical infrastructure of the global financial system.
Super apps differ fundamentally from traditional banking or payment apps by integrating multiple financial and non-financial services-payments, savings, credit, insurance, investments, shopping, mobility, and even entertainment-into one cohesive interface. Companies such as Grab in Southeast Asia and PayPal in the United States have progressively layered services to create ecosystems in which users can earn, spend, borrow, invest, and manage risk seamlessly. Analysts at McKinsey & Company and Bain & Company have repeatedly highlighted this ecosystem-based competition as a defining feature of the 2020s, and by 2026 it has become a core strategic lens for financial institutions in the United States, United Kingdom, Germany, Singapore, Brazil, and beyond.
From Mobile Banking to Orchestrated Financial Journeys
The evolution from simple mobile banking apps to full-fledged financial super apps has unfolded in stages, each one raising the bar for customer experience. In the early 2010s, banks and credit unions focused on digitizing branch-based services-checking balances, transferring funds, and paying bills-through mobile interfaces. This was followed by the neobank wave, led by firms like Revolut, N26, and Chime, which combined slick design with low-fee accounts and real-time notifications, setting new standards for user-centric design in markets such as the United Kingdom, Germany, and the United States.
The next phase saw platforms integrating adjacent services such as peer-to-peer transfers, budgeting tools, and basic investing, mirroring the rise of Cash App and Venmo in North America. However, the true inflection point came when companies began unifying multiple financial products, third-party services, and non-financial experiences into a single, orchestrated hub. In Asia, Grab and Gojek demonstrated how ride-hailing, food delivery, and payments could converge into a lifestyle platform; in China, Ant Group showed how digital wallets could expand into wealth management, credit scoring, and insurance at unprecedented scale, as documented by observers at the World Economic Forum.
In 2026, financial super apps are defined by their ability to anticipate user needs and orchestrate end-to-end journeys rather than isolated transactions. A customer in Canada or Australia might receive a personalized prompt within a super app to refinance a mortgage when interest rates fall, to adjust investment allocations in response to market volatility, or to purchase travel insurance when booking flights, all based on real-time analysis of transactional behavior, market data, and regulatory constraints. This orchestration relies heavily on APIs, open banking standards, and data-sharing frameworks such as those promoted by the Open Banking Implementation Entity in the United Kingdom and similar initiatives in the European Union under PSD2 and its successor regulations, which can be explored in more depth via the European Commission's digital finance pages.
For readers of FinanceTechX's fintech coverage, the implication is clear: competitive advantage is shifting from product-centric innovation to journey-centric platforms that can coordinate multiple services, often from different providers, into a coherent and trusted experience.
Redefining Customer Experience: Personalization, Context, and Trust
The defining promise of financial super apps is a radically improved customer experience that blends personalization, contextual relevance, and frictionless execution. To deliver on this promise, leading platforms are leveraging advances in data analytics, behavioral science, and machine learning, combined with intuitive design that minimizes cognitive load while maximizing perceived control.
Personalization in 2026 extends far beyond simple recommendations. Using transaction histories, location data, device signals, and consented third-party information, super apps can construct dynamic financial profiles that adapt to life stages and macroeconomic conditions. A young professional in the United States might see student loan optimization tools, automated savings nudges, and entry-level investment options, while a retiree in Germany or Japan might be presented with longevity planning, annuity products, and healthcare financing options. Resources such as the OECD's work on financial literacy and inclusion, accessible via the OECD website, underscore the importance of tailoring financial services to diverse demographic needs, a principle that super apps operationalize at scale.
Context-aware experiences are another key differentiator. When a user in Singapore pays for groceries, the super app might instantly categorize the expense, adjust a dynamic budget, offer targeted cashback offers, and suggest micro-investments of leftover change into diversified portfolios, drawing on guidance similar to that found on Investopedia. When a small business owner in Brazil issues invoices through the same platform, the app might automatically forecast cash flows, prompt the user about upcoming tax obligations, and offer short-term working capital based on transaction patterns and risk assessments.
However, such deep data integration raises fundamental questions of trust, privacy, and ethics. Regulators and consumer advocates, including those referenced by the U.S. Consumer Financial Protection Bureau, emphasize the need for transparent consent mechanisms, explainable algorithms, and robust data governance. Leading super apps increasingly embed privacy dashboards, granular permission controls, and plain-language explanations of data use, aligning with emerging standards such as the EU's General Data Protection Regulation (GDPR) and similar frameworks in countries like Canada and Brazil. Trust is no longer a static attribute conferred by a banking license or brand reputation; it is a continuously earned asset shaped by how platforms handle data, resolve disputes, and respond to incidents.
For FinanceTechX, which engages a readership deeply interested in the intersection of fintech, regulation, and consumer outcomes, this evolving trust equation sits at the heart of how financial super apps are redefining customer experience and reshaping the competitive landscape.
The New Competitive Arena: Banks, Fintechs, and Big Tech
The expansion of financial super apps has triggered a complex realignment among incumbent banks, fintech startups, and large technology platforms. Traditional banks in the United States, United Kingdom, Germany, and across Asia are no longer competing solely with peers on interest rates and branch networks; they are confronting ecosystem orchestrators that can aggregate demand, control interfaces, and capture data, often relegating banks to commoditized balance-sheet providers.
Some incumbents have responded by attempting to build their own super apps, integrating payments, personal finance management, investment services, and even non-financial offerings such as travel and retail partnerships. Others have opted to become infrastructure providers, offering banking-as-a-service capabilities to fintechs and non-banks, a trend documented by institutions like the Bank for International Settlements in their analyses of open finance. In markets such as Singapore and the United Arab Emirates, regulators have issued digital banking licenses specifically aimed at fostering innovative, app-centric models, encouraging both incumbents and challengers to experiment.
Fintechs, meanwhile, face a strategic crossroads. On one hand, they can strive to become super apps themselves, as Revolut and Paytm have attempted, bundling multiple services under a single brand. On the other hand, many fintechs are choosing to specialize deeply in narrow domains-such as cross-border remittances, alternative credit scoring, or niche investment products-and integrate into larger super app ecosystems through APIs and partnerships. This specialization aligns with the modular financial architecture that FinanceTechX frequently explores in its business and strategy analysis, where value is created by focusing on core capabilities while leveraging others' distribution.
Big tech companies, including Apple, Google, and Meta, have also intensified their financial ambitions, embedding payments, wallets, and credit products into their existing platforms. While they have not all embraced the full super app model, their control over operating systems, app stores, and advertising networks gives them immense leverage in shaping how users discover and engage with financial services. The interplay between big tech and super apps is particularly pronounced in regions like North America and Europe, where competition authorities such as the European Commission's Directorate-General for Competition scrutinize platform behaviors to prevent anti-competitive practices, as discussed on the European Commission competition pages.
In this environment, founders and executives featured in FinanceTechX's founders section are increasingly focused on ecosystem strategy: deciding whether to build, join, or supply super apps, and determining how to capture sustainable margins in a world where user attention and data are concentrated in a few dominant hubs.
Technology Foundations: AI, Cloud, and Embedded Finance
Behind the polished interfaces of financial super apps lies a sophisticated technology stack that integrates artificial intelligence, cloud-native architectures, and embedded finance capabilities. The ability to deliver real-time, personalized, and secure experiences at scale depends on these foundational technologies, which have matured significantly by 2026.
Artificial intelligence and machine learning are central to credit scoring, fraud detection, recommendation engines, and customer support. Models trained on vast datasets can identify anomalous behavior, flag potential identity theft, and tailor offers with remarkable precision. At the same time, regulators and standards bodies, including those referenced by the OECD and the European Banking Authority, emphasize the need for explainable AI and bias mitigation, recognizing the risks of algorithmic discrimination in lending and insurance. Leaders seeking to delve deeper into AI's implications for finance can explore resources from the Brookings Institution and the Harvard Business Review, which analyze governance frameworks and responsible innovation practices.
Cloud-native architectures enable super apps to scale elastically, support rapid experimentation, and integrate third-party services through microservices and APIs. Financial institutions that once relied on monolithic legacy systems have been compelled to modernize their infrastructure, often in partnership with hyperscale cloud providers such as Amazon Web Services, Microsoft Azure, and Google Cloud. This shift has significant implications for operational resilience and cybersecurity, topics that are closely monitored by regulators like the U.S. Office of the Comptroller of the Currency and international bodies such as the Financial Stability Board, whose work is available on the FSB website.
Embedded finance, the integration of financial services into non-financial customer journeys, is another pillar of the super app model. Through APIs and banking-as-a-service platforms, retailers, mobility providers, and digital marketplaces can offer payments, credit, and insurance at the point of need, while the underlying financial infrastructure is provided by licensed institutions. This model allows super apps to become the primary interface for diverse services without owning every component, creating a layered ecosystem in which value is distributed across banks, fintechs, and non-financial brands.
For FinanceTechX readers tracking the convergence of AI and finance, the platform's dedicated AI section provides ongoing analysis of how these technologies are reshaping product design, risk management, and customer engagement within the super app paradigm.
Regulatory, Security, and Risk Management Challenges
The rapid expansion of financial super apps has introduced complex regulatory and security challenges that cut across jurisdictions and sectors. Supervisors in the United States, European Union, United Kingdom, Singapore, and other key markets are grappling with how to oversee platform-based financial ecosystems that blur the boundaries between banking, payments, commerce, and social media.
One major concern is systemic risk. When millions of users depend on a single super app for payments, savings, and access to credit, operational failures or cyber incidents can have cascading effects across the economy. Central banks and regulators, including the Bank of England and the Monetary Authority of Singapore, have intensified their focus on operational resilience, mandating robust stress testing, incident reporting, and contingency planning. Readers can explore these evolving frameworks through the Bank of England's financial stability publications and MAS's digital finance initiatives.
Data protection and cybersecurity are equally critical. Super apps accumulate vast amounts of sensitive personal and financial data, making them prime targets for sophisticated cyberattacks. Compliance with regulations such as GDPR, the California Consumer Privacy Act (CCPA), and sector-specific cybersecurity guidelines requires continuous investment in encryption, identity verification, threat detection, and incident response. Organizations like ENISA in Europe and NIST in the United States publish best practices and frameworks, accessible via the NIST cybersecurity pages, which many super app providers use as reference standards.
Competition and consumer protection authorities are also scrutinizing the market power of super apps, particularly in regions like Europe and North America where concerns about digital gatekeepers are acute. Issues such as self-preferencing, data portability, and interoperability are at the forefront of policy debates, with potential implications for how super apps integrate third-party services and share data with rivals. These debates echo earlier discussions around big tech platforms and are likely to shape the regulatory environment for super apps for years to come.
Within this context, FinanceTechX has devoted increasing attention to security and regulatory topics in its security coverage, recognizing that trust in super apps depends not only on user experience but also on the robustness of underlying risk management and compliance frameworks.
Implications for Jobs, Skills, and the Future Workforce
The rise of financial super apps is transforming labor markets and skills requirements across the financial services industry and adjacent sectors. As banks and fintechs reorient around platform-based models, demand is growing for professionals in data science, AI engineering, cybersecurity, product management, and digital experience design, while traditional roles in branch operations and manual back-office processing continue to decline.
In the United States, United Kingdom, Germany, India, and Southeast Asia, super app providers are building multidisciplinary teams that combine financial expertise with software engineering, behavioral economics, and regulatory knowledge. Universities and professional associations are responding by updating curricula and certification programs, often drawing on guidance from organizations such as the Chartered Financial Analyst (CFA) Institute, which provides insights on evolving finance careers through its CFA Institute resources.
At the same time, the gig economy and platform work models associated with super apps in sectors like mobility and delivery have raised questions about worker protection, fair compensation, and social safety nets. As more financial services are embedded into these platforms-such as instant payouts, micro-savings, and income-smoothing credit-there is an opportunity to improve financial resilience for gig workers in markets from Brazil and South Africa to Thailand and New Zealand. Policymakers, labor organizations, and think tanks like the International Labour Organization (ILO) and the World Bank are actively studying these dynamics, with resources available via the World Bank's digital economy pages.
For professionals and job seekers following FinanceTechX's jobs insights, the message is that future-proof careers in finance will require fluency in data, technology, and regulation, alongside traditional financial acumen. Super apps are not just changing how customers interact with money; they are redefining what it means to work in financial services.
Capital Markets, Crypto, and the Super App Ecosystem
Financial super apps are also reshaping access to capital markets and digital assets, democratizing investing while raising new questions about investor protection and market integrity. Many leading platforms now offer commission-free trading of stocks and exchange-traded funds, fractional share investing, and simplified access to global markets, often inspired by pioneers like Robinhood and Trade Republic. As a result, retail participation in equity markets has surged in countries such as the United States, Canada, and parts of Europe, as documented by exchanges and regulators whose perspectives can be explored via resources like the U.S. Securities and Exchange Commission.
Cryptoassets and tokenized instruments have become another frontier for super apps. While regulatory approaches vary significantly-from more permissive regimes in parts of Asia and Latin America to stricter oversight in the European Union and the United States-many platforms now integrate crypto wallets, stablecoin payments, and access to tokenized securities. Institutions such as the International Monetary Fund (IMF) and the Bank for International Settlements have published extensive analyses on the macro-financial implications of crypto and digital money, available through the IMF's fintech and digital money pages.
For readers of FinanceTechX's stock exchange and crypto coverage, the convergence of traditional and digital assets within super apps is a critical trend. It enables investors in markets from the Netherlands and Switzerland to South Korea and Japan to manage diversified portfolios within a single interface, but it also concentrates market access in a handful of platforms, magnifying operational and conduct risks that regulators are still learning to address.
Green Fintech, Sustainability, and Global Impact
As environmental, social, and governance (ESG) considerations move to the center of corporate and investor agendas, financial super apps are beginning to integrate sustainability features that influence consumer behavior and capital allocation. Some platforms now provide carbon footprint estimates for transactions, offer green investment portfolios, and partner with environmental organizations to support reforestation or renewable energy projects. These initiatives align with global efforts led by institutions such as the United Nations Environment Programme Finance Initiative (UNEP FI), which promotes sustainable finance frameworks and can be explored via the UNEP FI website.
In Europe, where regulations like the EU Taxonomy and the Sustainable Finance Disclosure Regulation (SFDR) are reshaping investment products, super apps are experimenting with tools that help users understand the ESG impact of their portfolios and spending habits. In Asia and Africa, there is growing interest in using super apps to channel micro-savings into climate-resilient infrastructure and inclusive green projects, leveraging the reach of mobile-first platforms in countries such as Kenya, Nigeria, India, and Indonesia.
For FinanceTechX, whose loyal readers increasingly engage with green fintech and environmental themes, the emerging intersection between super apps and sustainability represents both a business opportunity and a responsibility. By embedding ESG insights into everyday financial decisions, super apps can influence millions of users worldwide, from North America and Europe to Asia, Africa, and South America, contributing to a more sustainable financial system if designed and governed thoughtfully.
Top Considerations for Leaders
As financial super apps continue to redefine customer experience in 2026, leaders across banking, fintech, technology, and regulation face a series of strategic choices that will shape the next decade of financial services. Institutions must decide whether to build their own super app capabilities, partner with existing platforms, or focus on specialized roles within broader ecosystems. They must invest in data, AI, and cloud infrastructure while strengthening governance, cybersecurity, and compliance to meet rising expectations from regulators and customers alike.
For founders and executives, the challenge is to balance scale with trust, personalization with privacy, and innovation with resilience. For policymakers, the task is to create regulatory frameworks that foster competition and inclusion without stifling beneficial innovation or allowing excessive concentration of power. For professionals and the future workforce, success will depend on continuous learning and adaptability in a landscape where technology, regulation, and customer behavior are evolving in tandem.
Within this complex environment, FinanceTechX positions itself as a key guide, curating news, analysis, and expert perspectives across global financial trends, economic developments, and industry news. As financial super apps become the primary interface between individuals, businesses, and the financial system, the need for clear, authoritative, and forward-looking insight has never been greater. By tracking the interplay of technology, regulation, customer experience, and sustainability, FinanceTechX aims to equip its audience across the United States, Europe, Asia, Africa, and the Americas with the understanding necessary to navigate and shape the next chapter of digital finance.
